

 Investment Team Voices Home Page
Taking Some Chips Off the Table Paid Off in 3Q
October 1, 2026
Eli Pars, CFA
Summary Points:
- After double-digit gains in the second quarter, the global convertible market gave back some ground, with the FTSE Global Convertible Index returning -4.6%.
- Calamos Global Convertible Fund (CXGCX) was much more resilient than the market during the quarter, returning -1.3%; performance benefited from our ongoing rebalancing away from the most equity-sensitive names.
- Convertible issuance stayed strong over the quarter; year-to-date issuance pushed past the $200 billion mark—a new record for a calendar year with three months left to go.
As we noted in our last commentary, the global convertible market shot the lights out during the second quarter, delivering in three months what we’d be happy to see in a year. But those sorts of quarters are few and far between—and it’s important to know when to leave the party.
Many times over the years, we’ve written about how convertibles don’t typically outperform equities. A lot of investors have avoided that truth this year and gotten caught up in the excitement of the high-flying AI companies coming to the convertible market.
What convertibles bring to the table is the opportunity for upside participation with a level of downside mitigation when equity markets fall. But getting those benefits requires active management. Convertibles vary in their levels of equity sensitivity, and, as we’ve discussed in the past, the greater the equity sensitivity, the greater the convertible’s exposure to the upside and downside of its underlying equity.
In our approach, we focus on convertibles that offer attractive risk-reward skew—we want to capture positive equity moves, but not to the extent that we give up all the downside cushion. During the quarter, Calamos Global Convertible Fund proved far more resilient than the global convertible market because our rebalancing paid off. While we weren’t able to completely sidestep the damage (especially in July), we believe that we avoided the worst of it. We actively sold off high-delta names that were trading close to their equities and replaced them with new issues that offered a better risk-reward skew.
Global Convertible Issuance: Breaking Records
During the third quarter, global convertible new issuance topped $66 billion. Issuance fell short of the second quarter’s nearly $84 billion, but it was nothing to sneeze at and more than enough to push global calendar-year issuance past the $200 billion mark, a new record. We’re optimistic that healthy issuance will continue, especially given the rise in interest rates, which provides an incentive for companies to issue attractively structured convertibles instead of non-convertible bonds. (In exchange for upside equity participation, investors will typically accept lower coupons.) How the anticipated IPOs of Anthropic and OpenAI play out is a bit of a wildcard—if they perform well, that should bolster sentiment around AI and AI convertibles more broadly. And, on the other hand, if they don’t perform well, that’s a good reason to own AI converts versus AI equities.
New Heights: Year-to-date issuance tops $200 billion
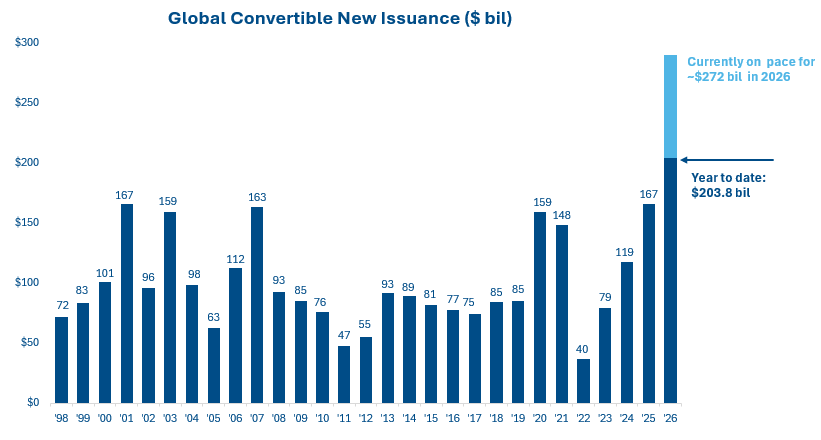
Source: BofA Global Research. Year to date through 9/30/2026.
We’ll keep doing what we’ve been doing
We’re sticking to our selective approach, staying mindful of position size and equity sensitivity. Although there’s been a lot going on under the hood due to our rebalancing, our largest sector and regional allocations are quite similar to where they were at the start of the quarter. Information technology issues make up roughly one-third of the portfolio, followed by consumer discretionary, with industrials, health care and communication services rounding out the top five sectors. Regionally, US issues make up about two-thirds of the fund, followed by Emerging Asia at a bit over one-sixth.
From a macro standpoint, there’s a lot of cloudiness on the horizon. US midterms are approaching fast, and there’s no shortage of geopolitical turmoil, but the US equity market is just a bit off all-time highs. The P/Es of large-cap firms aren’t unreasonable, but there’s still fuzziness in the “E.” Add to that a Fed raising rates—likely in part to slow down the equity market—and it’s hard to predict what the events will be, much less the outcomes of those events. Periods like this can last for a long time, which makes the case for using convertibles for lower-volatility equity participation.
| Total Return % as of 9/30/26 | 3Q26 | 1 Year | 3 Year | 5 Year | 10 Year | Fund Inception |
|---|---|---|---|---|---|---|
| Calamos Global Convertible Fund (CXGCX) | -1.31 | 13.23 | 16.31 | 5.35 | 8.73 | 7.74 (12/31/14) |
| FTSE Global Convertibles Index | -4.59 | 12.56 | 16.88 | 6.11 | 8.78 | 7.69 |
Source: Morningstar. Performance data quoted represents past performance, which is no guarantee of future results. Current performance may be lower or higher than the performance quoted. Please refer to important Risk Information. The principal value and return of an investment will fluctuate so that your shares, when redeemed, may be worth more or less than their original cost. The funds’ gross expense ratio as of the prospectus dated 2/27/2026 is 1.08% for Class I Shares.
Before investing, carefully consider the fund’s investment objectives, risks, charges and expenses. Please see the prospectus and summary prospectus containing this and other information which can be obtained by calling 1-866-363-9219. Read it carefully before investing.
Diversification and asset allocation do not guarantee a profit or protect against a loss.
Indexes are unmanaged, do not include fees or expenses, and are not available for direct investment. The FTSE Global Convertible Index is designed to broadly represent the global convertible bond market. The MSCI World Index measures the performance of developed market equities.
Opinions, estimates, forecasts, and statements of financial market trends that are based on current market conditions constitute our judgment and are subject to change without notice. The views and strategies described may not be appropriate for all investors. References to specific securities, asset classes and financial markets are for illustrative purposes only and are not intended to be, and should not be interpreted as, recommendations.
Important Risk Information. An investment in the Fund(s) is subject to risks, and you could lose money on your investment in the Fund(s). There can be no assurance that the Fund(s) will achieve its investment objective. Your investment in the Fund(s) is not a deposit in a bank and is not insured or guaranteed by the Federal Deposit Insurance Corporation (FDIC) or any other government agency. The risks associated with an investment in the Fund(s) can increase during times of significant market volatility. The Fund(s) also has specific principal risks, which are described below. More detailed information regarding these risks can be found in the Fund’s prospectus.
The principal risks of investing in the Calamos Global Convertible Fund include equity securities risk consisting of market prices declining in general, growth stock risk consisting of potential increased volatility due to securities trading at higher multiples, foreign securities risk, emerging markets risk, currency risk, geographic concentration risk, American depository receipts, midsize company risk, small company risk, portfolio turnover risk and portfolio selection risk.
Foreign security risk. As a result of political or economic instability in foreign countries, there can be special risks associated with investing in foreign securities, including fluctuations in currency exchange rates, increased price volatility and difficulty obtaining information. In addition, emerging markets may present additional risk due to potential for greater economic and political instability in less developed countries.
026077g 1026